
Categories
Financing a Maui home purchasePublished September 10, 2026
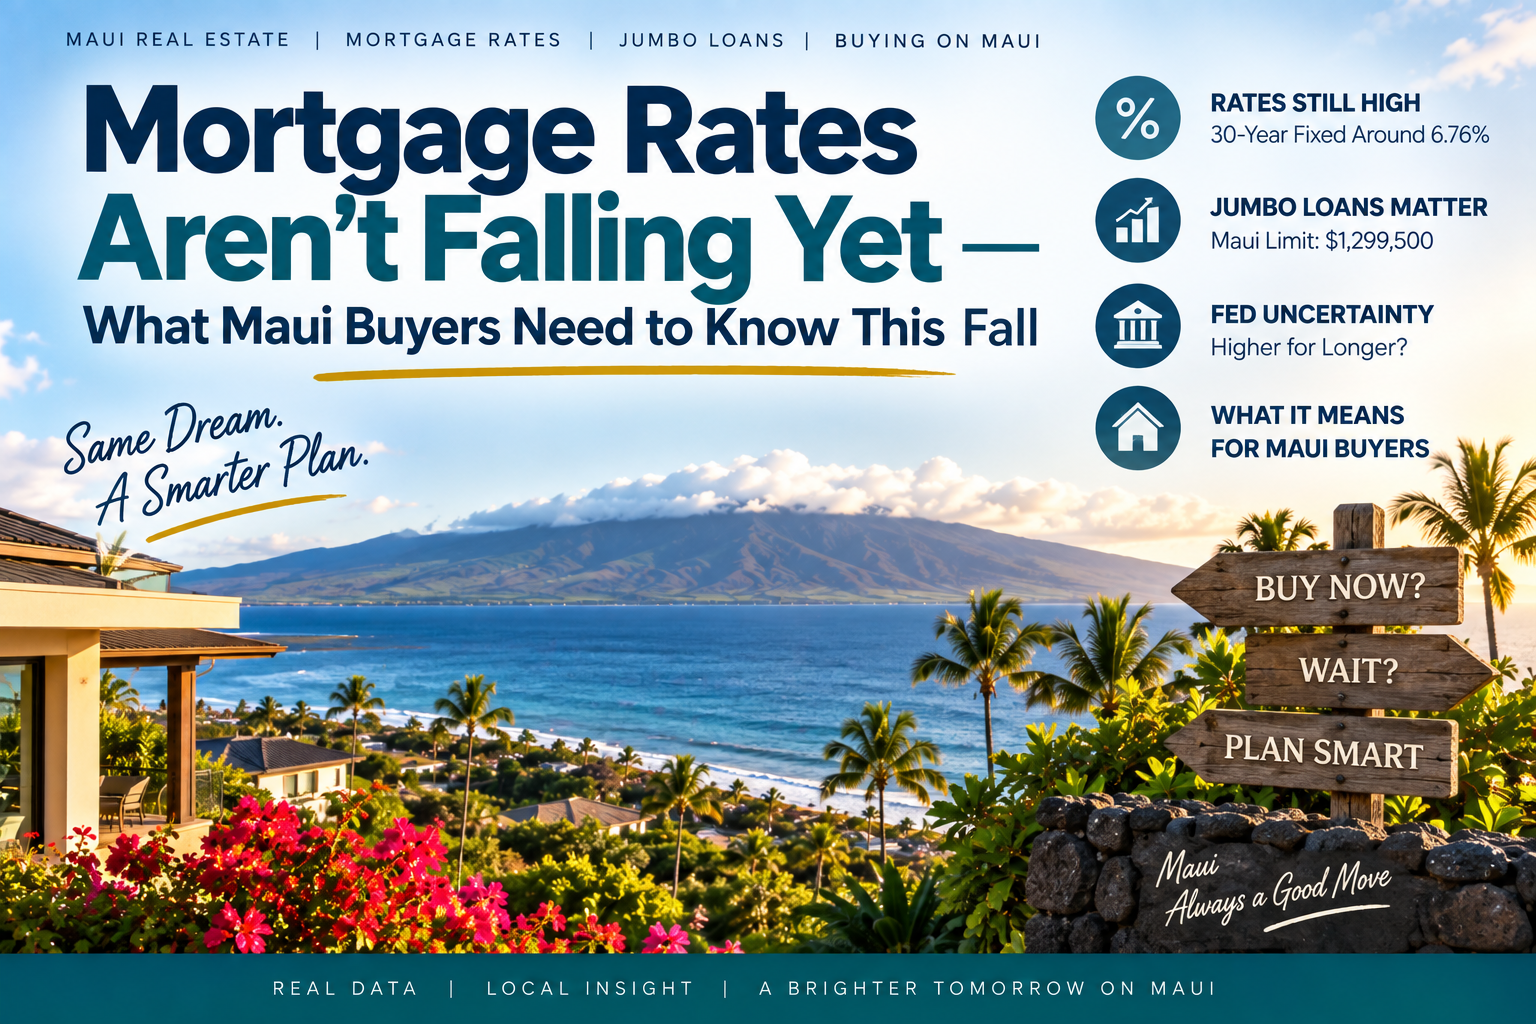
Mortgage Rates Aren't Falling Yet — What Maui Buyers Need to Know This Fall
Mortgage Rates Aren't Falling Yet — What Maui Buyers Need to Know This Fall
If you've been sitting on the sidelines waiting for mortgage rates to drop before making a move on Maui, here's the uncomfortable reality: that strategy may be getting riskier.
Heading into September 2026, mortgage rates remain elevated, the Federal Reserve has not started cutting rates again, and markets are now pricing in a meaningful chance of another rate increase.
For anyone considering a condo in Kihei, a home in Upcountry, or an investment property in Wailea, Kapalua, or elsewhere on Maui, understanding what is actually happening with rates right now matters more than relying on the assumption that lower rates are just around the corner.
Quick Answer: As of early September 2026, the average 30-year fixed mortgage rate is around 6.76%, with jumbo loans slightly higher at roughly 6.84%. The Federal Reserve held its benchmark rate at 3.50%–3.75% at its July meeting, but three members voted for a rate increase. After a stronger-than-expected August jobs report, markets increased the odds of a September rate hike to roughly 60%. For Maui buyers, where many purchases fall into jumbo-loan territory, waiting specifically for rates to fall may be a riskier strategy than it appears.
Where Mortgage Rates Stand Right Now
As of early September 2026, the average 30-year fixed mortgage rate is approximately:
6.76%
Jumbo 30-year mortgage rates are running slightly higher, at around:
6.84%
The average 15-year fixed mortgage is around:
6.12%
Mortgage rates have moved around throughout 2026, but the broad story has remained frustratingly consistent for buyers: rates are still high compared with the ultra-low-rate years, and there has not been the sustained decline many buyers expected.
For Maui, that matters even more because loan sizes are often much larger than they are in most mainland markets.
Why Jumbo Loans Matter So Much on Maui
The 2026 conforming loan limit for a one-unit property in Maui County is:
$1,299,500
That is considerably higher than the national baseline conforming loan limit of $832,750.
Maui qualifies for the higher limit because it is considered a high-cost housing market.
Even with that higher threshold, many Maui purchases still fall into jumbo-loan territory, particularly in areas such as:
- Wailea
- Makena
- Kapalua
- Kaanapali
- South Maui
- West Maui
- Higher-end Upcountry communities
A jumbo loan is generally a mortgage that exceeds the conforming loan limit.
Jumbo loans can come with different underwriting requirements than conforming mortgages, including:
- Larger down payments
- Higher reserve requirements
- Stricter debt-to-income standards
- More documentation
- Stronger credit requirements
- Different appraisal standards
That means a relatively small change in interest rates can have a meaningful impact on affordability when you're financing $1.5 million, $2 million, or more.
Why the Fed Isn't Cutting — And Could Still Hike
The rate cut many buyers have been waiting for hasn't materialized.
At its July 29 meeting, the Federal Reserve held the federal funds target range at:
3.50%–3.75%
But the decision wasn't unanimous.
Three Federal Open Market Committee members — Beth Hammack, Neel Kashkari, and Lorie Logan — voted instead for a quarter-point rate increase.
That is important because it shows that at least part of the Fed remains concerned that monetary policy may not be restrictive enough.
The primary reason is still inflation.
Inflation Is Still Above the Fed's Target
The Federal Reserve's preferred inflation measure, the Personal Consumption Expenditures Price Index, was running at approximately:
3.7% year-over-year
Core PCE, which excludes food and energy, was around:
3.3%
Both remain well above the Fed's long-term 2% inflation target.
That makes aggressive rate cuts difficult.
The Fed has repeatedly emphasized that it wants greater confidence that inflation is moving sustainably toward 2% before easing policy significantly.
For buyers, that means there is no guarantee that mortgage rates will decline simply because economic growth slows or because people expect the Fed to cut.
The August Jobs Report Changed Expectations
The August employment report, released September 4, 2026, added another complication.
The U.S. economy added approximately:
162,000 jobs
The unemployment rate remained around:
4.1%
That was stronger than many economists expected.
A stronger labor market reduces the immediate pressure on the Fed to cut rates and can increase concern that inflation will remain persistent.
After the employment report, markets sharply increased the probability of another Fed rate increase.
As of September 8, futures markets were pricing roughly:
A 60% chance of a rate hike at the September Federal Reserve meeting
The remaining probability largely favored the Fed holding rates steady.
The probability of a rate cut was extremely low.
The Next Big Date: September 11
The next major economic report to watch is the August Consumer Price Index.
That data is scheduled to be released:
September 11, 2026
The Federal Reserve then meets September 15–16.
If inflation comes in hotter than expected, the odds of a rate hike could rise further.
If inflation cools substantially, the Fed could choose to hold rates steady instead.
But as of now, buyers should not build their Maui real estate strategy around the assumption that rates are about to fall.
What This Means If You're Buying a Home on Maui
For buyers who have been waiting for lower mortgage rates before making an offer, it may be worth reframing the decision.
Instead of asking:
"When will rates drop?"
A more useful question may be:
"Can I comfortably afford the right property at today's rate and today's price?"
Mortgage rates and home prices do not always move in the same direction.
If rates eventually decline, more buyers could re-enter the market.
That can increase competition.
It can also put upward pressure on prices.
So waiting for a lower mortgage rate does not automatically guarantee a lower monthly cost.
Waiting Can Create a Different Kind of Risk
Imagine a buyer finds a Maui condo for $900,000 today.
They decide to wait because they believe mortgage rates will fall.
Six months later, maybe the mortgage rate is lower.
But if stronger demand pushes the condo price to $975,000, some or all of the savings from the lower rate can disappear.
The opposite could also happen.
Prices could fall.
Rates could rise.
Or both could remain relatively unchanged.
The point is that trying to perfectly time both mortgage rates and real estate prices is extremely difficult.
Even professional economists frequently miss rate forecasts.
Lock In What You Can Control
If you find a property that makes sense financially, talk with your lender about rate-lock options.
A mortgage rate lock can protect you from interest-rate movement during the period between contract and closing.
Depending on the lender, rate locks may be available for:
- 30 days
- 45 days
- 60 days
- Longer periods in some situations
Some lenders also offer float-down options that allow buyers to benefit if rates fall substantially after the lock.
The exact terms vary by lender, so this is something to discuss before writing an offer.
Get Pre-Approved Before You Start Shopping
On Maui, I strongly recommend getting fully pre-approved before seriously touring properties.
This is especially important if you may need jumbo financing.
A strong pre-approval helps you understand:
- Your realistic purchase price
- Your estimated monthly payment
- Required down payment
- Reserve requirements
- Closing costs
- Debt-to-income limits
- Whether the property type is financeable
This can save a tremendous amount of time.
It also reduces the risk of falling in love with a property only to discover that the financing doesn't work.
Ask About Seller-Paid Rate Buydowns
In a more balanced or buyer-friendly market, sellers may be willing to contribute toward financing costs.
One option is a seller-paid mortgage-rate buydown.
Instead of negotiating only on purchase price, a buyer may ask the seller to contribute funds toward reducing the mortgage interest rate.
Depending on the loan structure, this can sometimes produce a larger monthly-payment benefit than a modest price reduction.
For example, a seller credit used toward a permanent rate buydown may meaningfully lower the buyer's payment over the life of the loan.
Temporary buydowns can also reduce payments during the first one, two, or three years.
Adjustable-Rate Mortgages May Be Worth Considering
Some Maui buyers are also looking at adjustable-rate mortgages, commonly called ARMs.
An ARM typically offers a lower initial interest rate than a 30-year fixed mortgage.
For example, a 5/6 ARM may have a fixed rate for five years before adjusting periodically.
That can make sense for certain buyers who:
- Expect to sell within several years
- Expect income to increase
- Plan to refinance later
- Want a lower initial payment
- Are comfortable with future rate risk
ARMs are not right for everyone.
You need to understand the adjustment schedule, rate caps, and worst-case payment before choosing one.
Don't Assume You Can Refinance Later
One phrase I hear frequently is:
"I'll just refinance when rates come down."
That may happen.
But it should not be the foundation of your purchase decision.
There is no guarantee rates will fall within a specific timeframe.
You also need to qualify for the refinance later.
The property's value, your income, your credit, lending standards, and market conditions could all change.
A safer approach is to buy only if today's payment works.
If refinancing becomes available later, treat that as a bonus.
Maui Condo Buyers Have Additional Financing Issues
For Maui condo buyers, the interest rate is only part of the financing picture.
Certain condominium projects can be difficult to finance because of issues involving:
- Insurance coverage
- HOA reserves
- Deferred maintenance
- Litigation
- Commercial space
- Short-term rental operations
- Condotel characteristics
- Special assessments
A low mortgage rate doesn't help much if the building itself doesn't qualify for the financing you're expecting.
That's why lender selection matters.
A lender experienced with Maui condos can identify potential problems much earlier in the process.
My guide to financing a Maui condo in 2026 goes deeper into these issues.
What About Maui Condo Prices?
The Maui condo market has gone through a substantial correction over the past two years.
Prices remain well below recent peak levels in many segments.
At the same time, buyer activity has started increasing.
June and July 2026 both posted substantial year-over-year increases in condo sales, and August remained stronger than the previous year.
That creates an interesting situation.
Buyers currently have more negotiating leverage than they had during the peak market, while financing remains expensive.
If mortgage rates eventually fall, some of that buyer leverage could disappear as more people return to the market.
My latest Maui Condo Market 2026 update goes deeper into current pricing, transaction volume, and buyer leverage.
Should You Wait for Mortgage Rates to Fall Before Buying on Maui?
There is no universal answer.
Waiting may make sense if:
- Your current payment would be uncomfortable
- You need more time to save
- Your income isn't stable
- You don't know how long you'll own the property
- The properties you're considering don't currently make financial sense
But waiting purely because you are certain mortgage rates will decline soon is a different strategy.
Right now, the data does not support treating near-term rate cuts as a certainty.
The Fed may hold.
It may hike.
Inflation could remain stubborn.
Economic conditions could change.
Nobody knows exactly where mortgage rates will be six months from now.
The Better Way to Think About Timing
For most Maui buyers, I recommend focusing on four things:
Property. Price. Payment. Timeline.
Does the property fit what you actually want?
Is the price supported by recent comparable sales?
Can you comfortably afford the payment at today's rate?
And do you plan to own the property long enough that short-term market volatility becomes less important?
If the answers are yes, then trying to perfectly time the Federal Reserve may not add much value.
Frequently Asked Questions About Maui Mortgage Rates
What are mortgage rates on Maui right now?
As of early September 2026, average 30-year fixed mortgage rates are approximately 6.76%. Jumbo 30-year rates are around 6.84%, although actual rates vary based on credit, down payment, loan amount, lender, and property type.
What is the Maui conforming loan limit in 2026?
The 2026 conforming loan limit for a one-unit property in Maui County is $1,299,500.
What is considered a jumbo loan on Maui?
A mortgage above the Maui County conforming loan limit of $1,299,500 is generally considered a jumbo loan.
Are mortgage rates expected to fall in September 2026?
As of September 8, markets are not expecting a rate cut at the Federal Reserve's September meeting. Futures markets are pricing a meaningful probability of a rate increase, with the remainder largely favoring no change.
Will mortgage rates fall if the Fed cuts rates?
Not necessarily.
Mortgage rates are influenced heavily by longer-term bond yields and investor expectations, not simply the Federal Reserve's short-term policy rate.
A Fed cut can influence mortgage rates, but there is no guaranteed one-to-one relationship.
Is it better to buy now and refinance later?
That depends on whether the property and monthly payment make sense today.
A future refinance can potentially lower your payment, but buyers should not rely on refinancing as a certainty.
Are jumbo mortgage rates higher than conventional rates?
Sometimes.
Jumbo rates can be higher or lower than conforming rates depending on market conditions, lender appetite, borrower profile, and loan structure.
However, jumbo loans typically involve stricter underwriting.
Can a seller pay to lower my mortgage rate?
Potentially.
Seller credits can sometimes be used toward closing costs or mortgage-rate buydowns, subject to loan-program limits and lender rules.
The Bottom Line
Mortgage rates are not falling yet.
And as of early September 2026, there's a real possibility the Federal Reserve could raise rates again before the end of the month.
For Maui buyers, that makes financing strategy just as important as finding the right property.
This is especially true in a market where many purchases involve jumbo loans and where condo financing can come with additional layers of complexity.
The goal shouldn't be to perfectly predict the Fed.
The goal should be to understand what you can afford today, negotiate the best possible purchase terms, and buy the right property when the numbers make sense for you.
If you're considering buying a Maui home or condo and want to understand how current mortgage rates, jumbo financing, seller credits, or rate buydowns could affect a specific property, reach out anytime.
I'm happy to help you look at the real numbers and connect you with lenders who understand the Maui market.
Benjamin Finnerty REALTOR® RS-83812
Keller Williams Realty Maui RB-21851
808-481-9748
Benjamin@the808team.com
www.the808team.com
This article is provided for general real estate information only and is not financial, lending, tax, or legal advice. Mortgage rates, loan limits, underwriting requirements, market expectations, and Federal Reserve policy can change quickly. Buyers should verify current rates, loan terms, and eligibility directly with a qualified mortgage professional before making financial decisions.
The 808 Team Maui
| The 808 Team | Keller Williams Realty Maui
or another way