
Categories
Oceanfront Maui Rules and RegulationsPublished October 17, 2026
Buying Oceanfront Property on Maui: SMA and Shoreline Setbacks
Buying Oceanfront Property on Maui: Shoreline Setbacks, SMA Rules and Due Diligence
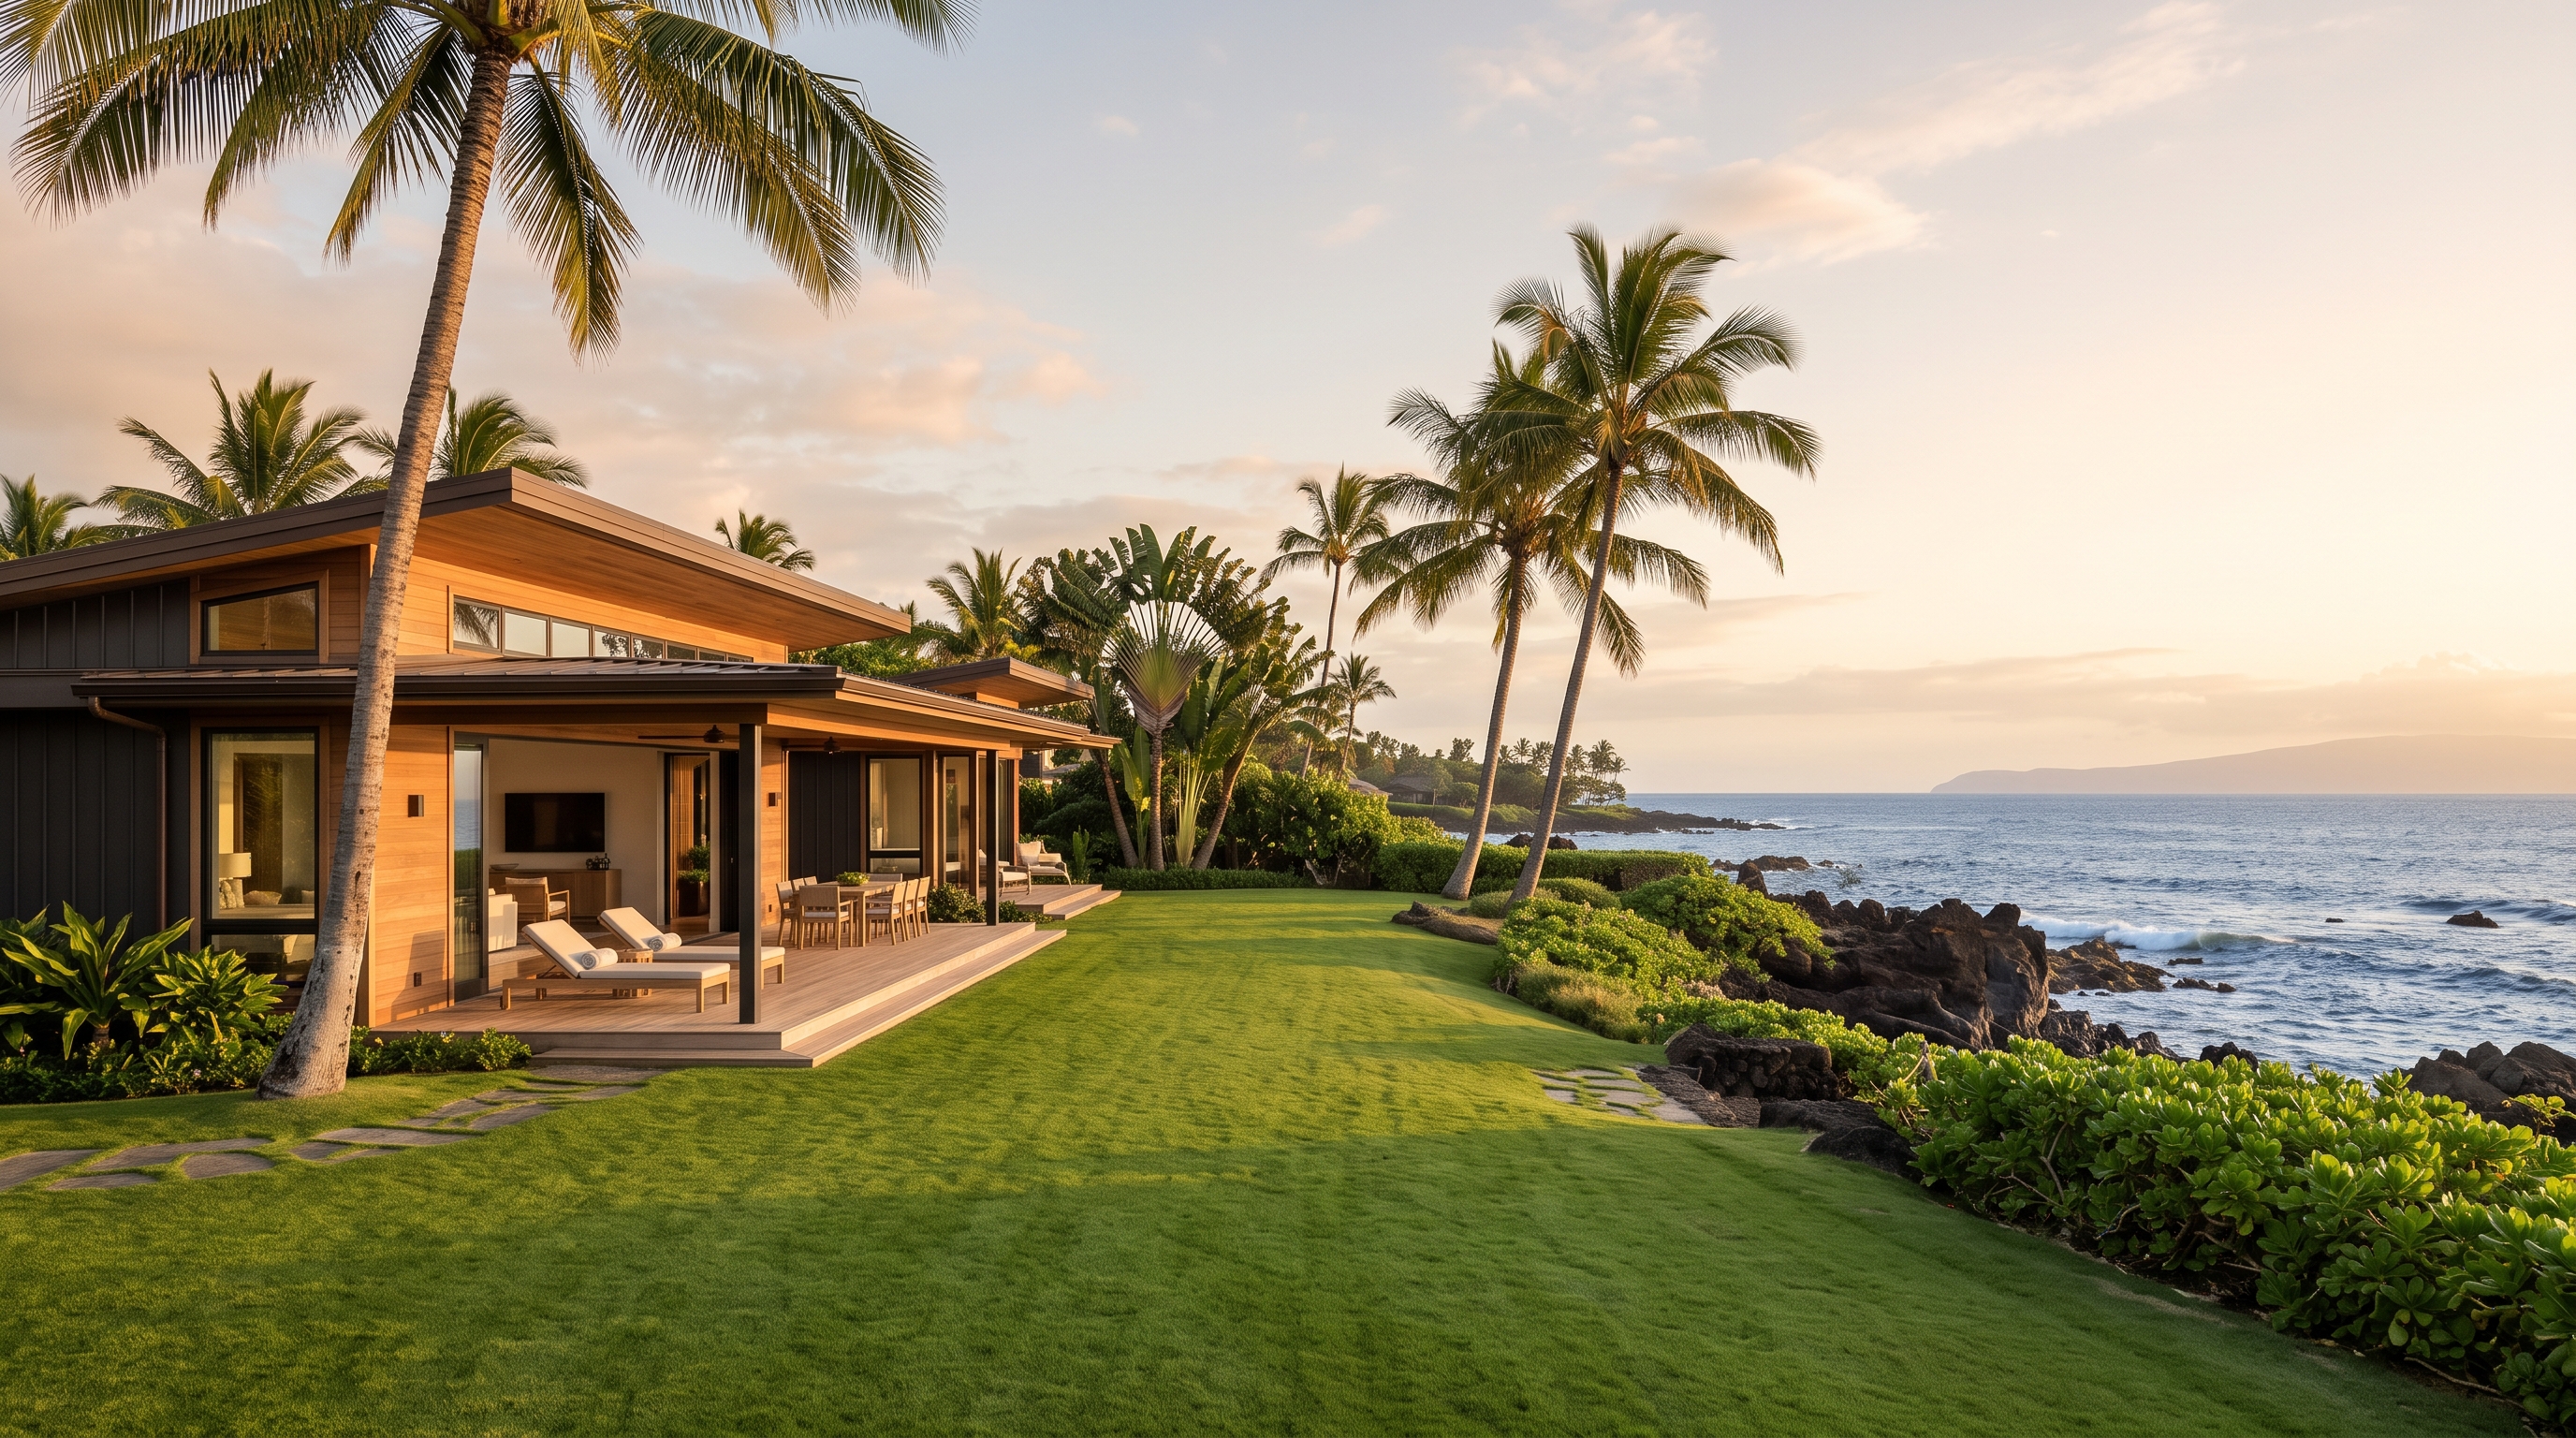
An oceanfront Maui property can be extraordinary. It can also carry constraints that are not obvious in listing photos or a standard home inspection.
Before buying near the shoreline, understand two related but different systems: the Special Management Area process and Maui’s shoreline setback rules.
These rules can affect what may be built, rebuilt, repaired, expanded or protected. That can directly affect what the property is worth for your intended use.
The goal is not to avoid every coastal property. It is to understand the risks and limitations that come with the specific property you are considering.
What Is Maui’s Special Management Area?
The Special Management Area, commonly called the SMA, is part of Hawaiʻi’s coastal-zone management system.
Development within the mapped SMA may require an assessment, exemption, minor permit or major permit depending on the work and current regulations.
Do not assume that ordinary-looking work is automatically exempt. “Development” has a specific legal meaning, and the correct permit path depends on the property and proposed activity.
Before buying, investigate:
- Whether the parcel is inside the SMA
- Which permits apply to the existing improvements
- Whether past additions and shoreline work were approved
- Whether permit conditions restrict future work
- Whether the buyer’s planned renovation would require new approval
A pool, retaining wall, deck, grading project, drainage improvement or expansion may involve requirements that are not apparent during a showing.
What Is the Shoreline Setback?
The shoreline setback is an area near the shoreline where development is restricted.
Maui Island’s updated Shoreline Rules took effect on August 25, 2024. The current system uses coastal-hazard science, including an Erosion Hazard Line based on projected erosion with 3.2 feet of sea-level rise.
Maui County states that the minimum setback is generally at least 40 feet from the shoreline.
Where no mapped Erosion Hazard Line exists, the rules may use a 200-foot setback or an optional lot-depth method, subject to minimum-buildable-depth provisions and a property-specific determination.
The County’s online Shoreline Setback Viewer is useful for preliminary planning. It is not a survey and does not establish an exact legal line on the ground.
Why the Rules Matter to Buyers
A home may be legal and valuable while having limited room for future work.
Buyers should distinguish among:
- Maintaining an existing permitted structure
- Repairing ordinary damage
- Remodeling within an existing footprint
- Expanding toward the ocean
- Replacing a structure after major damage
- Adding a pool, wall, deck or accessory structure
- Installing erosion-control or shoreline-hardening work
Different activities may face different standards.
The fact that a structure exists today does not necessarily prove that it could be rebuilt in the same size or location following a future loss.
That question should be investigated before closing—not after a storm, fire or insurance claim.
Can an Owner Build a Seawall?
Do not assume that a new seawall or similar structure will be approved.
Maui County explains that many shoreline-hardening structures—including seawalls, geotextile sea bags, groins and revetments—may require a shoreline setback variance from a regulatory prohibition. A variance may require approval by the Maui Planning Commission.
Shoreline armoring can affect beaches, erosion and public access. A buyer should never price a coastal property on the assumption that new hardening will be permitted.
If an existing seawall or erosion-control structure is present, determine whether it was properly authorized and what maintenance or repair rights apply.
Records to Review Before Buying
For an oceanfront or near-shore property, consider reviewing:
- The recorded survey and current title report
- Building permits and approved plans
- SMA assessments, exemptions and permit decisions
- Shoreline Setback Approvals or Determinations
- Shoreline setback variances
- Conditions attached to permits
- Certified shoreline surveys
- The County Shoreline Setback Viewer
- The mapped Erosion Hazard Line
- Flood-zone and flood-insurance information
- Coastal engineering and erosion reports
- Drainage and geotechnical reports
- Insurance availability and exclusions
- Condominium or community-association documents
- Records of storm damage and shoreline repairs
A coastal engineer, surveyor, attorney, architect, insurer and County planner answer different parts of the puzzle.
A REALTOR® can help organize the investigation and contract timeline but should not replace those licensed professionals.
Questions to Ask During the Inspection Period
Ask:
- Where are the legal shoreline and applicable setback lines?
- Is the existing home inside the current setback area?
- Were all structures and shoreline activities properly permitted?
- What maintenance and repair work is allowed?
- Could the structure be rebuilt after a major loss?
- Would my intended renovation require SMA approval?
- Is a seawall or hardening structure present?
- Is that structure permitted?
- What does the insurer assume about replacement?
- Are there pending violations, permit conditions or disputes?
Be specific when describing your intended use.
“Can I remodel?” may produce a very general answer.
“Can I add 400 square feet on the ocean side, replace the deck and construct a pool?” gives the County and appropriate professionals a clearer proposal to evaluate.
What Coastal Sellers Can Do
Coastal-property sellers should gather permit and shoreline records before listing.
If a buyer discovers an undocumented wall, deck or erosion-control project late in escrow, the uncertainty can be more damaging than a known and well-explained restriction.
Accurate marketing also matters. Avoid promising that a property is “buildable,” “protected” or “rebuildable” without documentation and a professional basis for the claim.
How Shoreline Constraints Affect Value
Ocean frontage does not eliminate land-use risk.
Two nearby properties with similar views may have very different:
- Redevelopment options
- Building envelopes
- Erosion exposure
- Insurance costs
- Permit histories
- Shoreline-protection rights
That is why coastal comparable sales require context.
A lower sale price may reflect condition, but it may also reflect a constrained building envelope or unresolved shoreline problem. A higher price may be supported by stronger documentation, a safer site position or properly permitted improvements—not simply the quality of the finishes.
Buyers can compare current opportunities through my Maui real estate search, including Wailea homes, Kāʻanapali homes and Kapalua homes.
Coastal buyers should also review current Maui home-insurance considerations before assuming that a property can be insured or rebuilt on expected terms.
Buying Along Maui’s Coast?
If you are considering an oceanfront home or condo, I can help you compare properties, obtain available real estate records, frame the right questions and build enough time into your offer for meaningful due diligence.
Call or text Benjamin Finnerty at 808-481-9748, email benjamin@the808team.com, or contact me online.
This article provides general real estate information, not legal, surveying, engineering, environmental, insurance or land-use advice. Confirm current requirements and property-specific conclusions with Maui County and the appropriate licensed professionals.
Talk to Benjamin Finnerty, Your Maui REALTOR®
This guide was written by Benjamin Finnerty (S), REALTOR® (RS-83812) with The 808 Team at Keller Williams Realty Maui, based in Kīhei. Whether you’re buying, selling or planning a move to Maui, I’m happy to answer your questions—no pressure.
Call or text: 808-481-9748
Email: benjamin@the808team.com
Website: benjamin.the808team.com
Keller Williams Realty Maui · 380 Huku Liʻi Place, Suite 201, Kīhei, HI 96753
Equal Housing Opportunity. Each office is independently owned and operated.
I follow federal and Hawaiʻi fair housing laws and work with everyone without regard to race, color, religion, sex—including gender identity or expression—sexual orientation, national origin, ancestry, familial status, marital status, disability, age or HIV status.
The 808 Team Maui
| The 808 Team | Keller Williams Realty Maui
or another way